Who You Are Working With
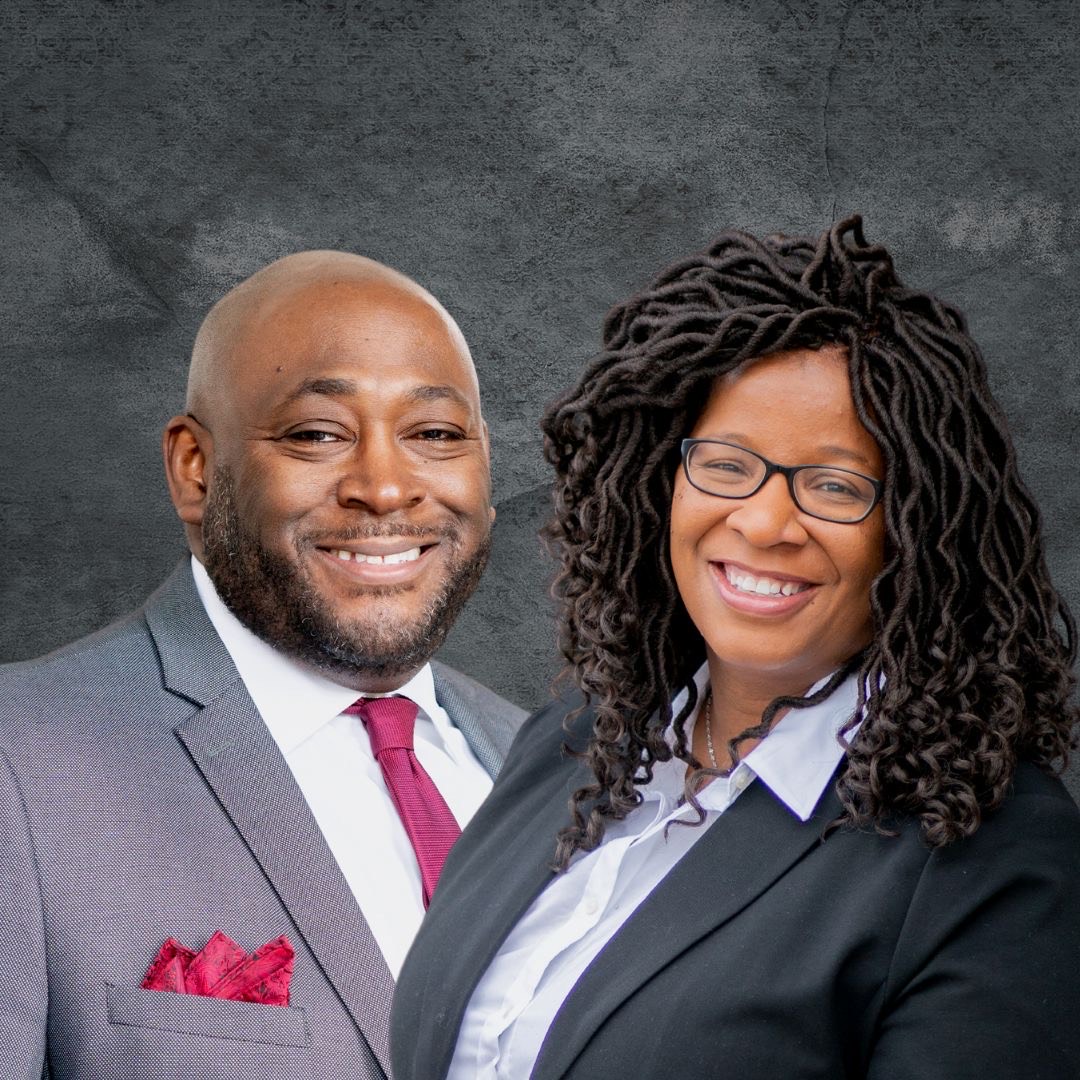
Kelly Jackson and Keith Jackson founded KJAX Group at Samson Properties and have sold more than 2,700 homes together. Kelly is licensed in DC, Maryland, and Virginia, and Keith is licensed in DC and Maryland. VA loan and Physician's Loan purchases are a specialty, and more than 40% of Kelly's business is military relocation.
Buyers work with us on first-time purchases using down payment assistance loans and grants and teacher programs, VA loan purchases for active duty service members and veterans, Physician's Loans for medical professionals, move-up purchases, 55+ moves, and luxury homes.
Kelly Jackson: Washingtonian Top Agent 2026 · DC Metro Real Producers Top 2%, Class of 2026 · ABR, GRI, e-PRO
How We Help Buyers
We start by understanding your goals, timeline, and finances, then guide you from the first showing through settlement with clear communication and steady coordination.
Know What a Home Is Worth
A market analysis of recent nearby sales before every offer, so you do not overpay.
Know the Community
HOA and condo fees, what they cover, and the rules that affect how you would use the home.
Win the Right Home
Offer terms built on how fast similar homes are selling, whether that calls for competing or negotiating.
Close on Time
Inspections, appraisal, loan deadlines, and settlement managed for you, typically in 30 days or less from contract.
The Buyer Process
Our buyers typically go from signed contract to settlement in 30 days or less, after a search that can take a few days or a few months. Here is what happens at each step and how long it typically takes.
Consultation and Buyer Agreement
Day oneWe talk through your goals, timeline, budget, and areas. Before the first showing, you sign a written buyer agreement that spells out our services and our fee. In your offer, we ask the seller to cover that fee.
Pre-Approval and Financing Plan
Usually within a few daysA full pre-approval tells you your real budget and makes your offer stronger. This is where we match you with the right loan, including VA loans, Physician's Loans, and first-time buyer down payment assistance programs.
Home Search and Community Research
A few days to a few monthsWe tour homes with you, or preview them for you if you are relocating. For each home you are serious about, we find out what you need to know about the community, including HOA or condo fees, what they cover, and any rules or restrictions that affect how you would use the home.
Market Analysis, Offer Strategy, and Negotiation
Usually one to three days to a ratified contractBefore you write an offer, we prepare a market analysis of what similar homes nearby have actually sold for, so you do not pay more than the home is worth. Then we set price, terms, and contingencies based on how fast those homes are selling. Fast-moving homes call for a clean, competitive offer. Homes that have been on the market a while leave room to negotiate.
Inspection, Appraisal, and Contingencies
Typically the first two weeks under contractWe schedule the home inspection, review the results with you, negotiate repairs or credits, and track the appraisal and loan approval deadlines in your contract.
Final Walkthrough and Settlement
Typically 30 days or less after ratificationWe confirm your final numbers, walk through the home before settlement to make sure it is in the agreed condition, and coordinate with the title company so closing day has no surprises.
Ready to Talk Next Steps?
If you are actively exploring homes and want clear guidance on next steps, let's talk. Call or text 240.385.9905.
Buyer Situations We Commonly Support
First-Time Buyers
Step-by-step guidance on pre-approval, down payment programs, inspections, and what to expect from contract to closing.
Move-Up Buyers
Coordinating the sale of your current home with your purchase, so the timing and the money line up. See our seller services.
Military and PCS Moves
Search plans built around your report date, with previews and virtual tours when you cannot be in town. See military relocation and buying with a VA loan.
Medical Professionals
Residents, fellows, and physicians matching at Johns Hopkins, UMMC, and other DMV hospitals, including Physician's Loan guidance. See our Johns Hopkins and UMMC guide.
55+ and Downsizing
One-level living, age-restricted communities, and timing a sale with your next move. See 55+ real estate in the DMV.
Luxury Buyers
Targeted search, discreet showings, and negotiation for higher-value homes across DC, Maryland, and Northern Virginia. See our luxury buyer services.
Buying in DC vs. Maryland vs. Virginia
DC, Maryland, and Virginia each have their own first-time buyer programs, transfer and recordation taxes, and seller disclosure rules, so the same price can mean very different cash at closing and very different information about the home. Kelly Jackson is licensed in all three, and Keith Jackson in DC and Maryland, so we can compare your options across state lines before you choose where to buy.
Washington DC
First-time buyer help
DC's Home Purchase Assistance Program (HPAP) offers eligible buyers interest-free loans of up to $202,000 in gap financing plus up to $4,000 toward closing costs, based on income and household size.
Closing taxes
Sellers pay DC's transfer tax of 1.1% or 1.45%, depending on price. Qualifying first-time buyers can get a reduced recordation tax rate of 0.725% on homes up to $777,000, with income limits.
Seller disclosures
DC is strict. Sellers must give buyers a written disclosure statement covering the condition of the home and any known defects.
Maryland
First-time buyer help
The Maryland Mortgage Program offers home loans with down payment assistance for eligible buyers, and some counties add their own programs.
Closing taxes
Maryland's state transfer tax is 0.5%, usually split evenly between buyer and seller. First-time Maryland buyers who will live in the home can have their 0.25% share waived. County transfer and recordation taxes vary by county.
Seller disclosures
Maryland sellers give buyers either a disclosure statement listing known defects or a disclaimer statement selling the home as is. Even with a disclaimer, sellers must disclose known hidden defects that affect health or safety.
Virginia
First-time buyer help
Virginia Housing offers a down payment assistance grant that does not have to be repaid, for eligible first-time buyers using a Virginia Housing loan, within income and price limits.
Closing taxes
Sellers pay Virginia's grantor tax of 50 cents per $500 of the price, about 0.1%. Buyers pay state and local recordation taxes.
Seller disclosures
Virginia is a buyer-beware state. Sellers make few disclosures about the home's condition, so your home inspection carries more weight.
We also work with teacher and public employee homebuyer programs, VA loans, and Physician's Loans, which can change how much cash you need at closing. Before you write an offer, we review the expected closing costs with you so the numbers are clear.
Program amounts, income limits, and tax rates change. Confirm current terms with your lender and title company before you rely on them. Sources: DC DHCD, HPAP; DC first-time buyer recordation rate; Maryland first-time buyer transfer tax exemption; Virginia Housing down payment assistance grant; Code of Virginia § 58.1-802.
Buyer Agreements and Who Pays Your Agent
Since August 2024, buyers must sign a written agreement with their agent before touring a home, and that agreement states what the agent will be paid. At KJAX Group, you sign the agreement at your first consultation, before the first showing, and in every offer we ask the seller to cover our fee. Depending on the final offer terms, the buyer may be responsible for some or all of it.
What the Agreement Covers
The buyer agreement spells out the services we provide, how long the agreement lasts, and the amount or rate of our compensation. We can never be paid more than the amount in your agreement. We go through it with you line by line before you sign, so there are no surprises.
Who Pays the Buyer's Agent Fee
We ask the seller to cover our fee in your offer, and sellers often agree as part of the deal. It is not automatic. Whether the seller pays all of it, part of it, or none of it depends on the offer terms you and the seller agree to, just like price, closing costs, and repairs. If the seller does not cover the full fee, the buyer is responsible for the rest under the buyer agreement. Before you write an offer, we show you how the request fits with the rest of your terms and what it means for your cash at closing.
VA and Other Loan Programs
VA loans and some other loan programs have specific rules about which costs a buyer can pay. We structure VA offers so those rules are followed and the offer stays competitive.
Buyer Tools and Resources
Search on your own time, then bring us the homes you like and we will run the numbers with you.
Home Search
Browse active MLS listings across DC, Maryland, and Northern Virginia, updated daily, and filter by the features that matter to you.
Search HomesBuying With a VA Loan
How buying with a VA loan works and how we keep VA offers competitive, from pre-approval through the VA appraisal.
VA Loan GuideMortgage Calculator
Estimate your monthly payment, including taxes, insurance, and HOA or condo fees, before you set your price range.
Calculator below ↓MORTGAGE CALCULATOR
Buyer Services FAQs
What is the first step when buying a home in DC, Maryland, or Virginia?
Start with a consultation to talk through your goals, timeline, budget, and areas, then get a full pre-approval so you know your real budget. You sign a buyer agreement before your first showing. To schedule a consultation with Kelly Jackson and Keith Jackson of KJAX Group, call or text 240.385.9905.
Do I have to sign a buyer agreement before touring a home?
Yes. Since August 2024, buyers must sign a written agreement with their agent before touring a home. The agreement states the services the agent provides, how long it lasts, and what the agent will be paid, and the agent can never be paid more than that amount.
Who pays the buyer's agent fee?
It depends on the offer terms. In every offer, we ask the seller to cover our fee, and sellers often agree as part of the deal. If the seller does not cover all of it, the buyer is responsible for the rest under the buyer agreement. We show you how the request affects your cash at closing before you write the offer.
How long does it take to buy a home in the DC area?
The search can take a few days or a few months, depending on your timing and the market. Once you are under contract, our buyers typically go from signed contract to settlement in 30 days or less.
How do you make sure I do not overpay for a home?
Before you write an offer, we prepare a market analysis of what similar homes nearby have actually sold for. That shows what the home is really worth, how fast similar homes are selling, and whether to compete or negotiate.
Do you work with VA loan buyers?
Yes. VA loan purchases are a specialty, and more than 40% of Kelly Jackson's business is military relocation. We plan the search around your report date, preview homes and set up virtual tours when you cannot be in town, and structure VA offers to follow VA rules while staying competitive.
What is a Physician's Loan?
A Physician's Loan is a mortgage designed for doctors and other medical professionals that may allow a low down payment and treat student loans and new employment contracts differently from a standard loan. We help residents, fellows, and physicians, including those matching at Johns Hopkins and UMMC, plan a purchase around their start date.
Are there first-time homebuyer programs in DC, Maryland, and Virginia?
Yes. DC's Home Purchase Assistance Program offers eligible buyers interest-free loans of up to $202,000 plus up to $4,000 toward closing costs. The Maryland Mortgage Program offers loans with down payment assistance, and Virginia Housing offers a down payment assistance grant that does not have to be repaid. We also work with teacher and public employee programs. Program terms and income limits change, so confirm current details with your lender.
How are closing taxes different in DC, Maryland, and Virginia?
In DC, sellers pay a transfer tax of 1.1% or 1.45%, and qualifying first-time buyers can get a reduced recordation tax rate of 0.725%. In Maryland, the 0.5% state transfer tax is usually split between buyer and seller, and first-time Maryland buyers can have their share waived, while county taxes vary. In Virginia, sellers pay a grantor tax of about 0.1%, and buyers pay state and local recordation taxes.
What do sellers have to disclose in DC, Maryland, and Virginia?
DC is strict: sellers must give buyers a written disclosure statement about the condition of the home. Maryland sellers give either a disclosure statement or a disclaimer statement selling the home as is, but must still disclose known hidden defects that affect health or safety. Virginia is a buyer-beware state with few required disclosures, so the home inspection carries more weight.
What contingencies should buyers expect in an offer?
Common contingencies include financing, appraisal, home inspection, and title review. The right mix depends on how fast similar homes are selling and how much risk you are comfortable with, and we walk through the trade-offs with you before you write the offer.
Ready to Start Your Home Search?
Start with a consultation. Kelly Jackson and Keith Jackson of KJAX Group will walk you through your budget, your loan options, and what homes are really selling for in the areas you are considering, before you tour a single home. Call or text 240.385.9905.
Related services:Seller ServicesMilitary RelocationBuying With a VA LoanJohns Hopkins and UMMC55+ Real Estate